A distributor agreement can look complete in a Johannesburg boardroom and still fail at the first border crossing. The missed detail is often basic: the local entity cannot issue the right invoice, the distributor lacks a trade licence, or the sales system cannot meet a revenue authority’s reporting rules.
A sales distributor network Africa strategy needs country-level operating decisions before product ships. Through our B2B sales consulting and sales enablement Africa work, we help leadership teams connect commercial design with entity setup, tax compliance, governance and local execution across Southern Africa.
This guide addresses Mozambique, Zimbabwe and Botswana as of October 2026. Regulatory and tax positions can change, so an M&J team member and qualified local advisers should review the final market-entry plan before launch.
Start with the commercial model, not the contract
Choose the route to market before appointing a distributor. A distributor buys and resells in its own name. An agent typically introduces or arranges sales for a principal. A branch or locally incorporated company gives the enterprise more control over pricing, customer relationships and field teams, but it also creates direct local compliance responsibilities.
The right choice depends on your sales cycle, margin and need for customer data. If your product requires technical installation, warranty decisions or regulated after-sales support, do not hand every customer interaction to a lightly supervised distributor. Build clear service levels, stock rules and escalation authority into the operating model.
We usually ask four questions first:
1. Who invoices the end customer, and in which country?
2. Who carries inventory, credit risk and bad debt?
3. Who owns customer and pipeline data when the appointment ends?
4. Which party must hold the licence, tax registration and reporting capability required for the activity?
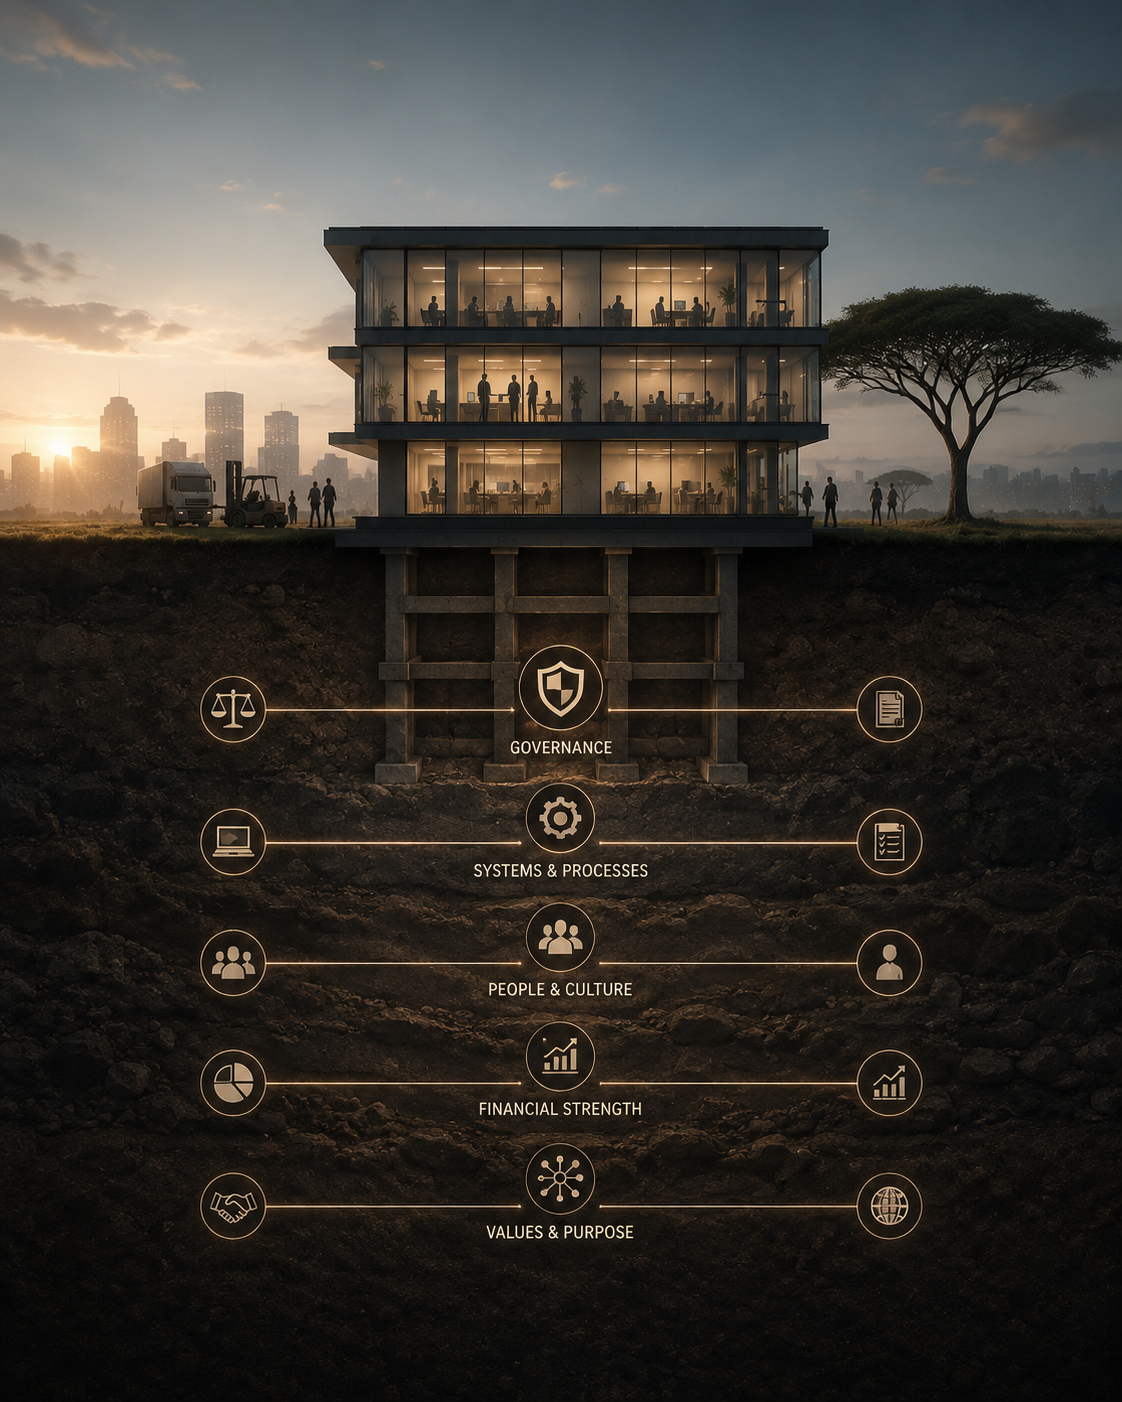
These questions determine far more than commission. They shape the entity structure, the forecast, the tax profile and the controls your regional leadership needs.
Set distributor economics before setting territory
Do not award national exclusivity because a prospective partner knows the market. Set measurable conditions first: annual purchase volumes, active-account targets, minimum stock, payment days, trained salespeople and reporting dates. Tie exclusivity to performance, with a review point that gives both parties a clear remedy.
A distributor margin only works when it absorbs the actual local cost to sell. Before signing, model landed product cost, trade licence fees where applicable, VAT treatment, sales salaries, warehousing, credit losses and promotional spend. A margin that looks sufficient before tax can leave no funding for market development after the first quarter.
Step 1: Build a country entry file for Mozambique
Mozambique requires a deliberate choice between a locally incorporated company, branch and commercial representative. A foreign company operating for more than one year must register a permanent branch. The Commercial Registry Office or Balcão de Atendimento Único handles company or branch registration, and operating activities require business licensing. This matters because appointing a local distributor does not automatically remove every local operating obligation.
Secure a NUIT early. The NUIT is the taxpayer identification number that supports tax compliance with the Mozambique Tax Authority. IVA and ISPC obligations have been exclusively online through the taxpayer portal since 1 June 2022, and normal-regime IVA uses the periodic Modelo A return. The finance team should confirm who prepares, approves and files each return before the first taxable sale.
If an investment project needs investment-law guarantees or incentives, register it with APIEX, IP. Under Decree 8/2024, the investment certificate evidences registration. The simplified-registration route has a decision period of three days after APIEX receives the file, but that timeline does not cure an incomplete file or replace business licensing.
What to include in the Mozambique distributor file
Keep one controlled file that records the NUIT, legal registration, operating licence, responsible tax officer, IVA treatment, sales territory and signed distributor authority. Ask the distributor to show the invoicing flow before go-live. The step teams skip most often is testing a real invoice and return process before the first customer order.
Take an illustrative equipment supplier planning US$300,000 of annual sales through Maputo. It appoints one distributor and assumes the partner’s company documents settle the market-entry work. During implementation, the parties discover they have not agreed who will make taxable supplies, file Modelo A or fund stock held for demonstrations.
The supplier should pause the first shipment, map the transaction from purchase order to invoice and assign each tax and licensing duty. A two-week design exercise can prevent months of disputed invoices and customer delays. If it were planning again, it would complete the NUIT, licensing and tax workflow before announcing a launch date.
Step 2: Design Zimbabwe sales operations around ZIMRA rules
Zimbabwe requires commercial teams to work closely with finance from day one. Register the trading entity and tax profile with the Zimbabwe Revenue Authority, ZIMRA. VAT registration becomes compulsory when taxable supplies exceed, or are expected to exceed, US$25,000 or the ZiG equivalent in 12 months.
The VAT rate is 15.5%, and VAT7 returns and payment fall due by the 25th of the following month. That deadline affects distributor cash planning. A distributor that collects late from retailers may still face its VAT obligation on schedule, so credit terms must reflect the working-capital reality.
All taxpayers, including enterprises below the VAT threshold, face fiscalisation requirements in Zimbabwe. Configure sales systems for reporting through the ZIMRA Fiscalisation Data Management System before the distributor goes live. Do not treat fiscalisation as a later finance project, because a field sales team cannot solve a system-design gap at the point of sale.
A foreign investor seeking a ZIDA general investment licence submits the prescribed application, company documents and beneficial-owner information. For a foreign investor, the application fee is US$500 and the licence-issuance fee is US$4,500 under SI 227 of 2023. Confirm whether your proposed structure and activity require this route before making a public investment commitment.
A practical Zimbabwe launch sequence
First, agree whether the distributor invoices customers in its own name or sells under a principal-led structure. Second, model the US$25,000 VAT threshold against the first 12 months of expected taxable supplies. Third, confirm fiscalisation capability, including how the distributor will report sales made in the field.
Take a retailer with twelve staff and a US$40,000 monthly payroll that adds a wholesale distribution unit. Its directors focus on supplier pricing, but the new unit expects taxable supplies well above the US$25,000 threshold. The finance manager then discovers that the chosen sales software does not support the intended ZIMRA fiscalisation process.
The retailer should budget for compliant system setup before it accepts the first distributor order, then build the 25th-of-the-following-month VAT7 date into its close calendar. This is not an optional back-office task. The director would likely choose a tested compliant sales system before negotiating a broader product range.
Step 3: Treat Botswana licensing as part of distributor due diligence
Botswana requires a business selling goods or services to hold a trade licence. The requirement covers activities described as agent, distributor and wholesale. Applications go through the relevant Town or District Council or the Ministry trade e-services portal, and the licence remains subject to annual fee payment.
This is a useful due-diligence test. Ask a prospective distributor to provide its current trade licence, the licensed activity description and evidence that its annual fee position is current. A company registration document alone does not demonstrate authority to undertake every trading activity.
VAT registration becomes compulsory when annual taxable supplies exceed P500,000. The Botswana Unified Revenue Service, BURS, identifies the standard VAT rate as 12%. Confirm the product’s treatment and filing category before setting distributor margins, because the wrong assumption can change the economics of every customer quotation.
Foreign managers need work permits supported by investment proof, premises evidence, company registration and a valid trade licence. Botswana Investment and Trade Centre, BITC, supports domestic and foreign investors through the Botswana One Stop Service Centre. Sequence those documents carefully if your model depends on a country manager or technical sales lead.
Avoid the Botswana documentation trap
Consider an illustrative regional manufacturer appointing a Gaborone distributor for industrial consumables. The company sends a foreign sales manager to support the launch, while the distributor begins trading before checking that its licence covers distributor or wholesale activity. The manager’s work-permit evidence then depends on documents that have not been aligned.
The manufacturer should separate the commercial appointment from the immigration and licensing workstream, while coordinating the evidence across both. It should also verify the distributor’s trade licence before assigning territory or sharing customer lists. With a second attempt, the business would set a document-completion gate before sales training and launch events.
Step 4: Govern the network after appointment
A signed agreement does not create a managed network. Establish a monthly operating review with a short, consistent pack: sales by customer, stock on hand, aged debt, active opportunities, returns, VAT and licensing exceptions, and forecast against target. The regional leader should see the same definitions in Maputo, Harare and Gaborone.
Set approval limits for discounting, customer credit and marketing spend. Distributor teams often ask for exceptions at quarter-end. A documented authority matrix protects margin and gives the country manager a clear basis for saying yes or no.
Customer ownership deserves equal attention. Record the account, contact, opportunity stage, next action and commercial owner in the customer relationship management process. If a distributor appointment ends, the enterprise needs an orderly way to preserve customer service without arguing over a spreadsheet.
Use a 90-day launch plan
Days 1 to 30 should close legal and tax readiness. Confirm the entity path, NUIT or tax profile, VAT status, licensing, fiscalisation requirements and required investment or work-permit documentation. No sales target should override a missing regulatory gate.
Days 31 to 60 should prepare the commercial engine. Train the distributor on product use, pricing authority, lead qualification, warranty handling and the customer-data process. Run the numbers through a VAT calculation and cash-flow model before finalising payment terms.
Days 61 to 90 should test execution with a defined customer segment. Review the first orders, invoices, sales-system reporting, delivery exceptions and collection cycle. This is where leadership sees whether the distributor has a sales network or only a contact list.
Frequently Asked Questions
Can we appoint one distributor for Mozambique, Zimbabwe and Botswana?
You can structure a regional appointment, but each country still has separate registration, licensing and tax requirements. Mozambique uses the NUIT and online Tax Authority compliance processes. Zimbabwe applies ZIMRA VAT and fiscalisation requirements. Botswana requires a trade licence for distributor and wholesale activities.
Does a distributor remove the need for our own local entity?
Sometimes, but not always. Your need for a local entity, branch or commercial representative depends on the activity, duration of operations and who sells, invoices and employs staff. In Mozambique, a foreign company operating for more than one year must register a permanent branch.
When does VAT registration become compulsory?
In Zimbabwe, compulsory VAT registration begins when taxable supplies exceed or are expected to exceed US$25,000 or ZiG equivalent in 12 months. In Botswana, the threshold is annual taxable supplies above P500,000. Confirm the position for the specific product and transaction model before contracting.
What should we check before signing a Botswana distributor?
Verify the current trade licence, including whether it covers distributor, agent, wholesale or the relevant activity. Confirm VAT position, premises evidence where relevant and the ability to support work-permit documentation if foreign managers will operate in Botswana.
Official sources reviewed
The country points in this guide draw on the Mozambique Tax Authority taxpayer portal, APIEX, IP investment materials and Decree 8/2024; ZIMRA VAT and fiscalisation guidance, plus Zimbabwe’s SI 227 of 2023; and Botswana Government trade-licence guidance, BURS VAT guidance and BITC investor support information. M&J should verify statutory details before publication, particularly where a proposed transaction has unusual product, ownership or employment features.
A well-run regional network gives leadership reliable market insight, controlled customer coverage and a defensible compliance position. Speak With Our Team through our B2B sales consulting and sales enablement Africa hub to plan the right route to market for Mozambique, Zimbabwe and Botswana.